I still remember the month I forgot to pay my credit card bill not because I didn’t have the money, but because I simply forgot. Late fee, dinged credit score, and that sinking feeling in my stomach for an entire week. That was the moment I decided I was done relying on my own memory and willpower to manage money. I needed a system that worked whether I remembered it or not. That’s when I started to automate your money, and honestly, it changed everything.
If you’ve ever missed a bill, forgotten to transfer money into savings, or looked at your bank account in confusion wondering where your paycheck went, this article is for you. We’re going to walk through exactly how to automate your money so your finances run quietly in the background while you focus on your actual life.
Table of Contents
- Why Willpower Is a Terrible Financial Strategy
- What It Really Means to Automate Your Money
- The Building Blocks of a Set-and-Forget System
- Best Budgeting Apps for the USA and UK
- Step-by-Step: Building Your Own Automated System
- Automating Debt Payoff Without Losing Your Mind
- Automating Investments (Even If You’re a Beginner)
- Common Mistakes People Make When They Automate Their Money
- How to Stay in Control Without Micromanaging
- Real-Life Example: A Month in an Automated System
- FAQ
- Final Thoughts
Why Willpower Is a Terrible Financial Strategy
Here’s an uncomfortable truth: most budgeting advice assumes you have unlimited discipline. Track every expense. Say no to every impulse buy. Remember every due date. Sit down every Sunday and review your spreadsheet.
That works for about three weeks. Then life happens you get busy, you get tired, you get distracted and the whole system falls apart. It’s not a personal failing. It’s just how humans work. We’re not built to make dozens of small financial decisions every single day and get them all right.
This is exactly why people automate your money in the first place. When you remove the decision entirely, you remove the chance of messing it up. You don’t decide whether to save this month the transfer already happened before you even saw the money. You don’t decide whether to pay the electric bill it’s already paid.
Financial freedom isn’t really about earning more or cutting every latte out of your life. It’s about designing a system so good that your finances improve automatically, even on your laziest, most chaotic days.
What It Really Means to Automate Your Money
When people hear “automate your money,” they often think it just means setting up autopay for bills. That’s part of it, but it’s a small part. A real set-and-forget financial system touches almost every part of your money life:
- Your paycheck gets split before you even see it
- Savings and investing happen without you lifting a finger
- Bills get paid on time, every time
- Debt gets chipped away automatically
- You get alerts if something looks off, so you stay informed without micromanaging
The goal is simple: reduce the number of manual decisions you have to make each month down to almost zero. When you truly automate your money, good financial behavior becomes the default, not something you have to fight for.
The Building Blocks of a Set-and-Forget System
Before jumping into apps and tools, it helps to understand the actual pieces you’re trying to connect. Think of these as the pipes in your financial plumbing system.
1. Direct Deposit Splitting
Most employers in the USA and UK let you split your paycheck across multiple accounts. This is the single most powerful tool when you automate your money, because it means savings happen before spending even becomes an option.
2. Automatic Transfers
Beyond your paycheck, you can schedule recurring transfers between accounts checking to savings, savings to investment accounts, and so on. This is the backbone of any system built to automate your money effectively.
3. Bill Pay and Autopay
Every recurring bill rent, utilities, subscriptions, loan payments should be set to pay automatically wherever possible. In the UK, this usually means setting up a Direct Debit; in the US, it’s typically called Autopay.
4. Budgeting and Tracking Apps
These apps sit on top of your accounts and give you visibility. They don’t move money themselves, but they tell you what’s happening so you can trust the system you built.
5. Alerts and Guardrails
Automation doesn’t mean going blind. Setting up low-balance alerts, spending notifications, and monthly summaries keeps you aware without requiring daily check-ins.
Best Budgeting Apps for the USA and UK
This is where a lot of people get stuck, because there are dozens of apps promising to fix your finances. Let’s cut through the noise. Below are the apps that genuinely help people automate your money, based on what they actually do well.
YNAB (You Need A Budget)
YNAB is built around a philosophy called “give every dollar a job.” It’s not the most passive tool you do need to categorize spending but it pairs beautifully with automated transfers because it shows you exactly where your automated savings are landing. Available in both the US and UK, with bank syncing for most major institutions.
Best for: People who want structure and don’t mind a short learning curve.
Monarch Money
Monarch has become one of the most popular replacements for Mint since Mint shut down. It offers a clean dashboard, net worth tracking, and collaborative budgeting if you share finances with a partner. It’s US-focused but expanding features regularly.
Best for: Couples who want shared visibility into automated systems.
Copilot Money
Copilot uses AI-assisted categorization and is beautifully designed, currently available on iOS. It’s excellent for people who want a budgeting app that feels effortless — which fits perfectly with the goal to automate your money without spending hours managing spreadsheets.
Best for: Apple users who value design and simplicity.
Rocket Money (formerly Truebill)
Rocket Money specializes in finding and cancelling subscriptions you forgot about, along with bill negotiation services. This is a fantastic companion tool once your automation is in place, since it catches the leaks in your system.
Best for: Anyone who suspects they’re bleeding money through forgotten subscriptions.
Emma (UK-Focused)
Emma is one of the most widely used apps for UK users to automate your money, offering subscription tracking, spending insights, and savings pots that sync with major UK banks.
Best for: UK residents wanting an all-in-one money app.
Plum and Moneybox (UK)
Plum and Moneybox both use algorithms to automatically move small amounts of money into savings or investments based on your spending patterns. These apps are practically the definition of set-and-forget, quietly helping you automate your money in the background using round-ups and rule-based saving.
Best for: People who struggle to save manually and want it done invisibly.
Empower (formerly Personal Capital)
Empower blends budgeting with investment tracking, which makes it a strong choice once your automated savings start flowing into investment accounts. It’s especially useful for US users tracking net worth over time.
Best for: People with investments who want a bigger-picture view.
There’s no single “best” app here the right one depends on whether you want deep control (YNAB), effortless simplicity (Copilot, Emma), or a tool that actively finds savings for you (Rocket Money, Plum). Many people actually combine two: one for bill tracking, one for investment visibility.
Step-by-Step: Building Your Own Automated System
Let’s get practical. Here’s how to actually automate your money, piece by piece, starting today.
Step 1: Map Out Your Fixed Expenses
List every recurring bill rent or mortgage, utilities, insurance, subscriptions, loan payments. Write down the amount and due date for each one.
Step 2: Open (or Confirm) Your Account Structure
A simple structure that works well:
- Checking/current account for bills and daily spending
- Savings account for your emergency fund
- Separate savings account or “pot” for specific goals (holiday, house deposit, car)
- Investment account for long-term wealth building
Step 3: Set Up Direct Deposit Splitting
Contact your employer or adjust it through your payroll portal so a percentage of your paycheck routes directly into savings and investment accounts before it ever touches your main checking account.
Step 4: Automate Every Bill You Can
Go through your list from Step 1 and switch everything to autopay or Direct Debit. Set due dates a day or two after payday whenever the provider allows it, so there’s always money available.
Step 5: Schedule Your Savings Transfers
If your employer can’t split your paycheck, set up an automatic transfer that happens the same day your paycheck lands not a week later, when the money’s already been spent on other things.
Step 6: Connect a Budgeting App
Link your accounts to whichever app fits your style from the list above. This becomes your dashboard, the place you check once a week (not daily) to confirm everything is running smoothly.
Step 7: Add Alerts
Set low-balance alerts and large-transaction notifications through your bank app. This is your safety net it means you’ll know instantly if something is wrong, without needing to watch your account like a hawk.
Once these seven steps are in place, you’ve genuinely started to automate your money in a way that requires almost no ongoing effort.
Automating Debt Payoff Without Losing Your Mind
Debt is one of the most emotionally exhausting parts of personal finance, which makes it a perfect candidate for automation. When you automate your money toward debt, you remove the temptation to skip a payment during a tight month.
Two popular strategies:
- Debt snowball pay minimums on everything, throw extra at the smallest balance first. Automate the minimums, and manually add extra payments once a month if you want more control over which debt gets the boost.
- Debt avalanche same idea, but extra payments go toward the highest-interest debt first. This saves more money mathematically.
Whichever method you choose, automate the minimum payments without exception. Missing a payment can trigger penalty interest rates and damage your credit score far more than the few dollars you might save by “waiting to see how the month goes.”
Automating Investments (Even If You’re a Beginner)
This is where automate your money turns from “avoiding late fees” into actually building wealth.
In the USA
- 401(k) contributions set to auto-deduct from your paycheck, ideally enough to get your full employer match. That match is free money; not claiming it is like automating a pay cut.
- Roth IRA set up automatic monthly contributions rather than trying to remember to fund it once a year.
- Robo-advisors like Betterment or Wealthfront can automatically invest and rebalance a diversified portfolio for you.
In the UK
- Workplace pensions auto-enrollment already does much of the work, but you can increase your contribution percentage for a stronger long-term outcome.
- Stocks and Shares ISA set up a standing order so a fixed amount invests every month, tax-free on growth.
- Robo-advisors like Nutmeg or Moneybox allow round-up investing and recurring contributions with minimal effort.
The beauty of automated investing is that it removes emotion from the equation. You’re not trying to “time the market” or deciding whether this month feels right to invest. The money goes in on schedule, rain or shine, which is historically one of the most reliable ways to build wealth over decades.
Common Mistakes People Make When They Automate Their Money
Even a good system can go wrong if you overlook a few things.
Automating before building a buffer. If your checking account sits right at zero after bills, one unexpected automatic payment can trigger overdraft fees. Keep a small buffer, even just $200-300, sitting in checking as a cushion.
Setting it and truly forgetting it. “Set-and-forget” doesn’t mean “never look again.” Check in monthly to make sure nothing has changed a subscription price increase, a bill that moved dates, or an account that quietly closed.
Automating savings but not automating spending limits. If your discretionary spending account has no cap, automation won’t save you from overspending there. Consider a separate account with a fixed automated deposit for fun money, so once it’s gone, it’s gone.
Ignoring irregular income. If you’re a freelancer or have variable income, automating fixed percentages instead of fixed dollar amounts tends to work better, since it flexes with what you actually earn.
Not updating automation after a raise or life change. Got a raise? Increase your automated savings percentage immediately, before your spending expands to match your new income. This is one of the fastest ways to actually automate your money into lasting wealth rather than lifestyle inflation.
How to Stay in Control Without Micromanaging
A lot of people worry that automation means losing touch with their finances. It’s actually the opposite, when done right. You’re not ignoring your money you’re removing the boring, repetitive parts so you can focus your attention on the decisions that actually matter, like whether to change careers, buy a home, or invest in a business idea.
A good rhythm looks like this:
- Weekly: A five-minute glance at your budgeting app to catch anything unusual
- Monthly: A slightly longer review check that automated transfers went through, bills were paid, and nothing needs adjusting
- Quarterly: A bigger picture check are your savings goals still relevant? Did your income or expenses change enough to adjust the automation?
- Annually: A full review of your entire system interest rates, investment performance, whether you’re still using the right budgeting app
This rhythm means you always automate your money while still staying the one in charge of it, not the other way around.
Real-Life Example: A Month in an Automated System
Let’s make this concrete. Say your paycheck lands on the 1st of the month.
- Day 1: Paycheck arrives. Automatically, 15% routes to a retirement account, 10% to a high-yield savings account, and the rest lands in checking.
- Day 2: Rent, phone bill, and streaming subscriptions are auto-paid via Direct Debit or autopay.
- Day 3: A robo-advisor automatically invests your monthly ISA or Roth IRA contribution.
- Day 5: Your budgeting app sends a weekly summary showing you’re on track.
- Day 15: A round-up savings app has quietly added another $12 from spare change on your coffee and grocery purchases.
- Day 28: You get a low-balance alert on a secondary account, so you glance at it, notice a forgotten subscription renewal, and cancel it in two minutes.
Notice what didn’t happen: you didn’t sit down and manually move a single dollar. You didn’t stress about a due date. You didn’t have to remember anything. That’s what it looks like when you genuinely automate your money the system does the heavy lifting, and you just steer occasionally.
FAQ
Is it safe to automate all my bills and savings? Yes, as long as you keep a buffer in your checking account and check in periodically. The risk isn’t automation itself it’s automating without a safety cushion or ignoring your accounts for months at a time.
What if my income is irregular? Automate percentages rather than fixed amounts, or automate only your baseline expenses and manually top up savings when a bigger paycheck comes in. Many freelancers still automate your money partially, even with variable income.
Which budgeting app is best for beginners? Copilot Money and Emma are known for being intuitive with minimal setup. If you want more hands-on control, YNAB tends to teach better long-term habits.
Do I need a financial advisor to automate investing? Not necessarily. Robo-advisors like Betterment, Wealthfront, Nutmeg, or Moneybox can automatically build and manage a diversified portfolio for a small fee, making it easy to automate your money into long-term investments without hiring a human advisor.
How much should I automate into savings each month? A common starting point is 20% of income split between short-term savings and long-term investing, but even 5-10% automated consistently beats a much larger amount saved inconsistently.
Will automation stop me from overspending? It reduces the temptation significantly because the money is gone before you see it, but it works best paired with a separate account for discretionary spending so you have a visible, capped amount to work with.
What’s the difference between automating in the US versus the UK? The main differences are terminology and account types Autopay versus Direct Debit, 401(k)/Roth IRA versus workplace pension/ISA but the underlying principle to automate your money is identical in both countries.
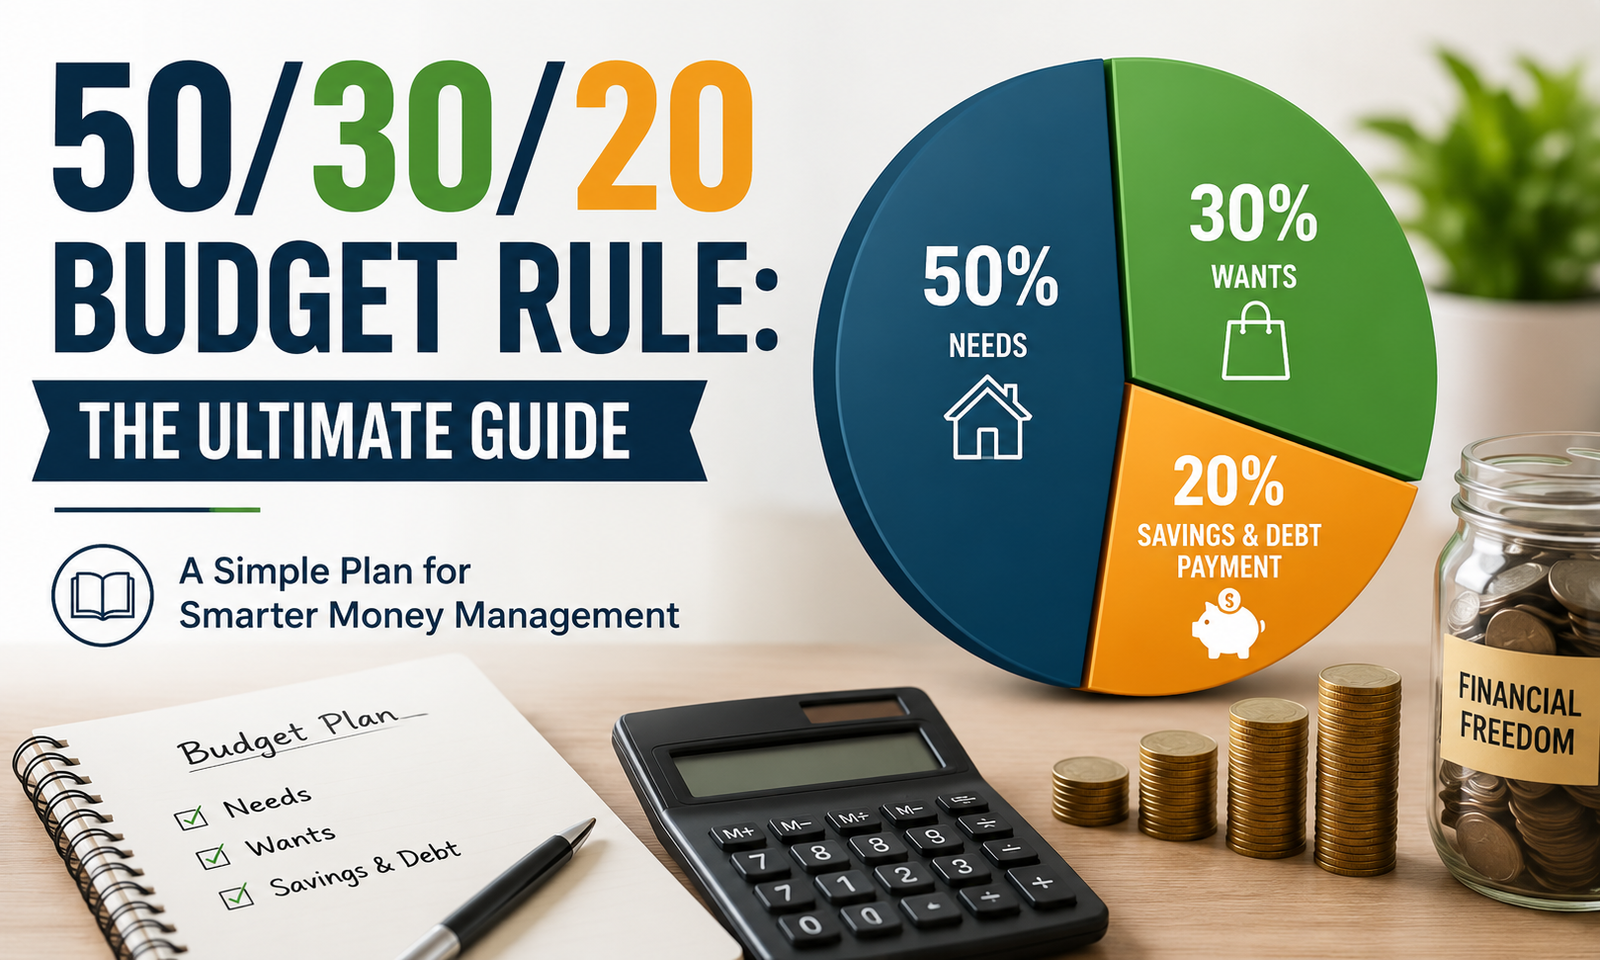
Read About 50/30/20 Budget Rule